If your business operates as an S Corporation or Partnership in Connecticut, you’ve likely heard of the CT Pass-Through Entity Tax (PET) election. It’s a planning opportunity that can meaningfully reduce your federal tax bill, but it comes with strict deadlines and penalties if you get the timing wrong. Here’s what you need to know.
What Is CT PET?
CT PET is an entity-level tax that S Corporations and Partnerships in Connecticut can elect to pay. It was originally created to help business owners work around the federal $10,000 cap on State and Local Tax (SALT) deductions. By having the entity pay the state tax directly, business owners can deduct that payment as a business expense on the federal return, effectively getting around the SALT cap. The election is no longer mandatory, but for many businesses it remains a valuable optional strategy.
How It Works
- The election is made on the timely filed CT-1065/CT-1120SI (Connecticut Composite Income Tax Return).
- It’s made annually, and once made for a given year, it’s irrevocable.
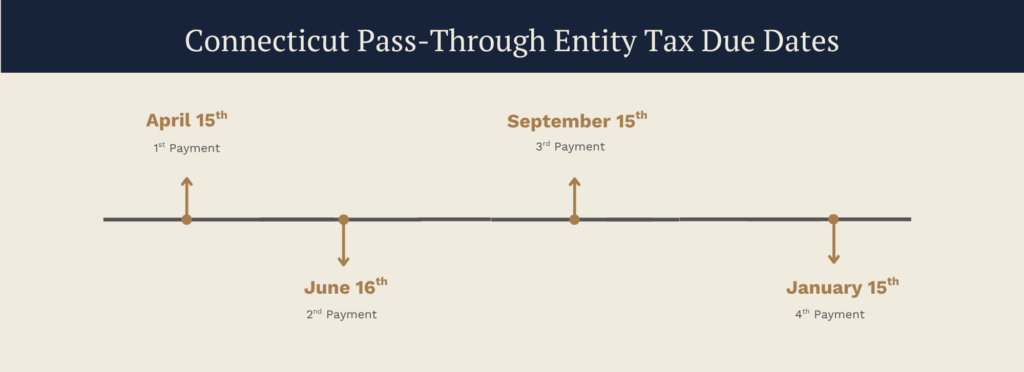
- If the annual tax is expected to be $1,000 or more, the entity must make quarterly estimated tax payments.
How to Calculate Estimated Payments
CT PET is calculated at 6.99% of your net income for the year. Each quarterly estimate should equal 25% of that amount.
If you’re unsure what your net income will be, you can instead base each 25% installment on a safe harbor amount — the lesser of:
- 90% of the current year’s tax liability, or
- 100% of the prior year’s tax liability
Paying at least this amount each quarter protects you from the underpayment penalty, even if your final liability turns out to be higher once the year is complete.
Penalties for Missed Payments
Missing a quarterly payment trigger both interest and a late payment penalty:
- A penalty applies to each missed installment, even if you make up the underpayment later in the year.
- Interest accrues at 1% per month (or fraction of a month) on the underpayment.
- Payments not made electronically are also subject to a penalty of 10% of the tax payment, up to $2,500.
How to Pay
Step 1. Estimated payments can be made through the myconneCT portal via direct payment (electronic withdrawal) or credit/debit card. Paying electronically isn’t just convenient; it is necessary to avoid the 10% non-electronic payment penalty noted above. Step 2. Scroll down to the “Pass Through Entity” section and select “Make an Estimated Payment.” 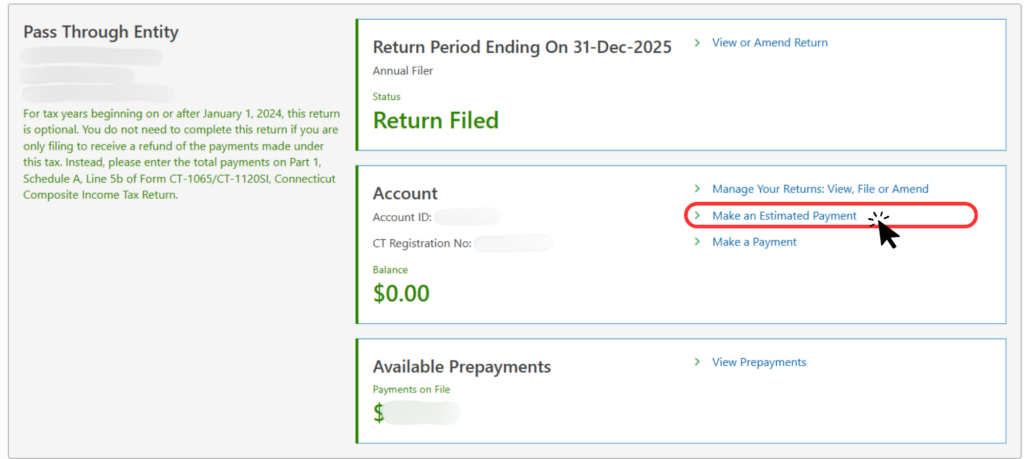 Step 3: Confirm that your Estimated Payment is being made for the correct Period End.
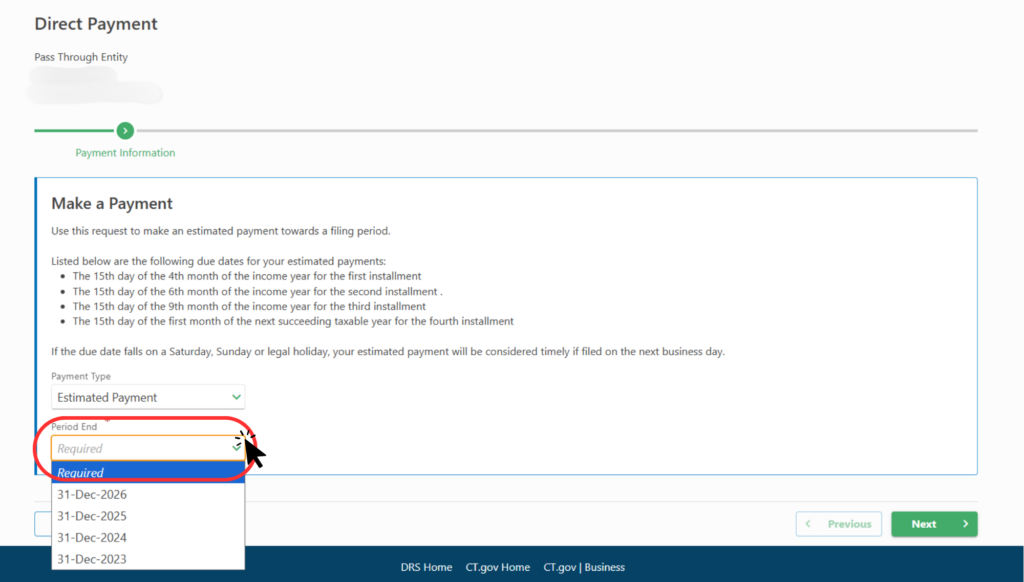
Step 4: Enter your payment information and you are all set!
Benefits of the CT PET Election
- The PET payment is a deductible business expense for federal income tax purposes.
- Each owner receives a corresponding tax credit on their personal Connecticut income tax return, equal to 87.5% of their share of the tax paid by the entity.
A Real-World Example
Consider a Connecticut partnership with two equal (50/50) partners and $200,000 of expected income. The total PET payment for the year would be $13,980, split into four equal quarterly installments of $3,495 (due April 15, June 15, September 15, and January 15). Each partner receives a CT K-1 showing their $6,990 share of the tax paid. On their personal Form 1040, each partner can claim a credit equal to 87.5% of that amount: $6,990 × 87.5% = $6,116.25 credit per partner Meanwhile, the full $13,980 state tax payment is deducted as a business expense on the federal return, reducing the partnership’s federal taxable income — which flows through to each partner’s K-1 and ultimately their Form 1040.
Is CT PET Right for Your Business?
The CT PET election is a tax planning tool, but the irrevocable nature of the annual election and the strict quarterly deadlines mean it’s worth getting professional guidance before you file. If you have questions about whether the election makes sense for your business, or need help with tax planning or consulting more broadly, schedule an appointment with our team.